
Land Tax Valuation NSW: What Every Investment Property Buyer Should Check Before Settlement
You’ve found the property, the numbers stack up, and you’re ready to sign the contract. But there’s a cost that catches a lot of first-time NSW investors off guard once settlement’s done and dusted: land tax.
Unlike stamp duty, which you pay once, land tax is an annual bill based on the land tax valuation NSW assessors place on your property each year — and it has nothing to do with what you paid for the place, or what it’s worth on the open market. It’s based purely on the value of the dirt underneath it.
If you’re weighing up an investment property purchase, understanding how this valuation works, what it’ll cost you, and how to check whether it’s fair can help you avoid unexpected costs and understand your options if property valuation disputes arise. Here’s what actually matters.
Summary
Land tax in NSW is calculated on the unimproved land value of any property you own that isn’t your principal place of residence, as determined annually by the NSW Valuer General. For the 2026 land tax year, you’ll pay nothing if your combined taxable land holdings sit below $1,075,000, and above that, tax is charged at $100 plus 1.6% of the excess (rising to 2% above $6,571,000). Because the threshold applies to your combined NSW landholdings — not per property — owning even one or two investment properties can tip you over it, especially in Sydney and other high-growth markets where land values have risen faster than the frozen threshold. If you disagree with the land value on your Notice of Valuation, you generally have 60 days to object through the NSW Valuation and Objection Portal, backed by comparable sales evidence. Before buying, factor land tax into your ongoing holding costs, check how the property’s land value compares to similar local sales, and consider getting an independent valuation if the Valuer General’s figure looks out of step with the market.
What Is Land Tax Valuation NSW and Why It’s Different to Your Purchase Price
The first thing to get your head around is that land tax valuation NSW authorities use has nothing to do with the contract price you negotiated, or a bank valuation used for your mortgage.
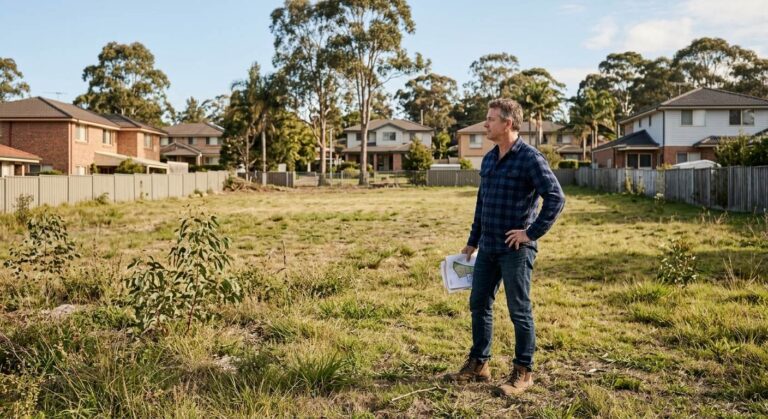
Land tax is assessed on unimproved land value — essentially, what the block would be worth if it were empty, because land value means the value of the land only, excluding buildings and structures. This value is set each year by the NSW Valuer General, a statutory role independent of Revenue NSW, and it forms the basis for both your annual council rates and your land tax bill.
This distinction trips a lot of buyers up. A renovated Federation home on a modest block in the inner west might have a relatively low land value despite a high sale price, while a knock-down house on a large corner block in a growth corridor could carry a surprisingly high land value even though the dwelling itself is worth little.
How the Valuer General Sets Land Values
The Valuer General’s office uses mass valuation techniques, analysing sales of similar vacant or near-vacant land across a suburb or zone, then applying that data across every parcel in the area. Land values are generally reassessed each year, with a full revaluation cycle occurring roughly every three years for many council areas. Your Notice of Valuation reflects the statutory land value used for tax purposes, and understanding why NSW land values lag behind market changes can help explain why your assessed value may differ from current property prices.
How Land Tax Is Calculated on an Investment Property
Once you own an investment property (or any land that isn’t exempt, like your own home), Revenue NSW aggregates the land value of everything you hold across NSW as at midnight on 31 December each year, and taxes you on the combined total.
For the 2026 land tax year, the settings are:
| Taxable land value | Land tax payable |
| Up to $1,075,000 (general threshold) | Nil |
| $1,075,001 to $6,571,000 | $100 plus 1.6% of the value above $1,075,000 |
| Above $6,571,000 (premium threshold) | $88,036 plus 2% of the value above $6,571,000 |
A useful thing to know: these thresholds have been frozen at their 2024 levels rather than indexed upward each year, which means as land values keep climbing in many parts of Sydney and regional NSW, more investors are being drawn into the system without buying anything new — simply because their existing land value has crept up.
Worked Example
Say you own one investment property with a land value of $1,250,000 (this is separate to the value of the house sitting on it).
- Excess above the general threshold: $1,250,000 − $1,075,000 = $175,000
- Tax on the excess: $175,000 × 1.6% = $2,800
- Plus the base amount: $2,800 + $100 = $2,900 in land tax for the year
If you already own another investment unit with a land value of $400,000, Revenue NSW adds both together ($1,650,000 combined), and the tax is calculated on the whole lot — not each property separately. That’s the trap for investors building a portfolio: your land tax bill accelerates faster than most people expect once you cross into two or three properties.
Foreign Owners: The Surcharge Land Tax
If you’re a foreign person buying residential land in NSW, there’s an additional surcharge land tax of 5% of the land value, payable from the very first dollar with no threshold at all. This applies on top of the standard land tax calculation and is a separate consideration that catches overseas-based buyers and some visa holders off guard.
Land Tax Valuation NSW and Exemptions Investors Should Know About
Not every property attracts land tax, and it’s worth understanding the main exemption before you assume your future home purchase or holiday house will be caught by it.
The Principal Place of Residence Exemption
Your own home is generally exempt from land tax, provided you actually live in it as your main residence. From the 2026 land tax year, this exemption comes with a tighter rule: the occupying owners must together hold at least a 25% ownership interest in the property. This matters if you’re buying with family members, or structuring ownership through a trust or company, since it can affect whether the exemption applies.
Investment Properties Don’t Qualify
An investment property — whether it’s tenanted, vacant, or being renovated between tenancies — generally does not qualify for the principal place of residence exemption. Even a property you intend to move into eventually is usually taxable until you actually occupy it as your home.
Common Misconception: “I Only Just Bought It, Surely I’m Not Liable Yet”
A lot of new investors assume land tax only applies from the following financial year, or gets prorated to their settlement date. In reality, liability is determined by who owns the land at midnight on 31 December, regardless of when during the year you settled. Buy in November, and you could be liable for the full year’s land tax the following year based on that snapshot date.
Checking or Challenging a Land Tax Valuation
If the land value on your Notice of Valuation looks out of step with what similar blocks are selling for in your area, you don’t have to simply accept it.
How to Object
You generally have 60 days from the date on your Notice of Valuation (or your land tax assessment notice) to lodge a formal objection under the Valuation of Land Act 1916. Objections are lodged online through the NSW Valuation and Objection Portal, and they need to be backed by evidence — typically at least three comparable land sales, with details of the sale price, date, and why each sale is genuinely comparable to your property.
A few practical points if you’re considering this:
- You need to lodge a separate objection for each property if you’re disputing more than one valuation.
- All your supporting evidence needs to be submitted at the time you lodge — there’s generally no second chance to add more later.
- A different valuer to the one who set the original figure will review your objection.
- Revenue NSW aims to resolve most objections within 90 days.
- If you’re not satisfied with the outcome, you can appeal to the NSW Land and Environment Court, generally within 60 days of the objection determination.
Why an Independent Valuation Can Help
Comparable sales evidence is the backbone of a successful objection, and pulling together the right sales — genuinely similar land, in the same catchment, sold around the relevant valuation date — isn’t always straightforward using public listings alone. This is where an independent property valuer can add real value: preparing a supportable land valuation report with properly analysed comparable sales gives your objection far more weight than a handful of listings pulled from a real estate website.
It’s also worth getting an independent valuation done before you buy, particularly for larger blocks, subdivision-potential sites, or properties in areas where land values have moved sharply. Knowing the likely land tax valuation NSW authorities will apply — before you’re locked into a contract — lets you factor the ongoing holding cost into your investment numbers properly, rather than discovering it after settlement.
Practical Considerations Before You Buy
Before signing on an investment property, it’s worth running through a few checks specific to land tax:
- Check your existing landholdings. If you already own investment property or vacant land in NSW, work out your combined land value before assuming a new purchase will stay under the threshold.
- Look at the land value, not just the price. Two properties at the same purchase price can carry very different land tax bills depending on land size, zoning, and location.
- Factor land tax into your holding costs. Alongside interest, insurance, council rates, and maintenance, land tax is a genuine annual cost that affects your cash flow and net yield.
- Consider ownership structure carefully. How you hold the property — individually, jointly, through a company, or via a trust — can affect thresholds and exemptions, and it’s worth discussing with your accountant or solicitor before settlement.
- Watch the 31 December snapshot date. If you’re settling late in the calendar year, understand that you may become liable for a full year’s land tax based on your ownership at that date.
FAQs
Does land tax apply to every investment property in NSW?
Only if your combined taxable land value across all your NSW holdings exceeds the general threshold ($1,075,000 for the 2026 land tax year). A single modest investment property might sit below this on its own, but combined with other landholdings it can push you over.
Is land tax based on my purchase price?
No. It’s based on the unimproved land value set annually by the NSW Valuer General, which can be higher or lower than your purchase price depending on how much of that price relates to the dwelling versus the land itself.
Can I object to my land value if I think it’s too high?
Yes, generally within 60 days of your Notice of Valuation, through the NSW Valuation and Objection Portal, supported by comparable land sales evidence.
Does land tax get prorated if I buy partway through the year?
No. Liability is assessed based on who owns the land at midnight on 31 December each year, not on a pro-rata basis from your settlement date.
Will my new investment property automatically be exempt if I plan to move in later?
No. The principal place of residence exemption generally only applies once you’re actually living in the property as your main home, not while it’s tenanted or vacant awaiting your move-in date.
Is land tax the same across every Australian state?
No. Thresholds, rates, and exemptions vary significantly between states and territories, so a NSW land tax calculation can’t be applied to a property in Victoria, Queensland, or elsewhere.
Conclusion
Land tax valuation NSW rules catch plenty of investors off guard because the figure is based on unimproved land value, not purchase price, and thresholds apply across your combined holdings. Before buying, check the land value, factor land tax into your holding costs, and don’t hesitate to challenge a valuation that looks out of step with comparable sales in the area.
Need a Second Opinion on a Land Valuation?
If a Notice of Valuation looks higher than comparable land in the area, or you simply want clarity on a property’s land value before you commit to buying, Expert Court Property Valuers can prepare an independent valuation report to support your position. You can reach the team on +61 438 080 786 to discuss your situation.